What Is Agentic Payments Infrastructure? (And Which Half Is Hype)
Agentic payments infrastructure, explained by people who build and sell it: what it is, the four controls buyers demand, how Natural, Authorized, and Skyfire define it differently, and which use cases are real in the next 12 months.

Quick answer: agentic payments infrastructure is the layer that lets an AI agent move money on a person's or company's behalf - card issuing, budgets, merchant restrictions, and an audit trail. Because KYC law requires a human or business behind every account, the real product isn't "a bank account for your agent." It's an allowance: a sandboxed card the agent can use, with limits it can't exceed.
We build this and we sell it - so below we also say which parts of agentic payments we think are hype.
What "agentic payments" actually means
You already know the ask-and-answer version of AI: you prompt, it responds. Payments become agentic when the AI stops waiting for prompts and starts completing tasks in the background - including the part where money changes hands.
Instead of just recommending shoes on Amazon, the agent says: I found them, I'll buy them for you. Give it a budget and it can take care of your groceries every week - working in the background and making payments on your behalf, just like a real assistant would.
Emil Aite, co-founder
The business case is just as plain. Every purchase is a workflow: research, decide, enter card details, shipping, confirm. Commerce has spent 15 years shaving seconds off that flow; an agent deletes it entirely. "Get the best sandwich near me within a reasonable delivery fee, don't spend over $20" is a complete procurement process in one sentence.
Consumers are moving faster than companies here. Instinct, one of the breakout personal-assistant agents, reports that roughly 40% of users hand over a personal credit card within their first weeks:
On the business side, nobody has asked us on a sales call to let an agent buy things - yet. But roughly 40% of our own website traffic is already bots and AI assistants reading pages for their humans. Checkout waves tend to arrive the way the ChatGPT-referral wave did: one or two, then suddenly it's the majority.
What goes wrong if you just hand the agent a company card
The same reason you don't give a smart intern a limitless credit card. Agents are good at following rules, but they sometimes misinterpret the goal - you say 'get me the best shoes' and it keeps hitting checkout in a loop. A spending limit is how you stay on budget, exactly like you do with employees today.
Emil Aite
Worst case is the email from American Express saying you're over your limit, and now you're explaining why a corporate card with a six-figure limit got maxed out by an agent. That's the nightmare every company in this space, including us, is designing out of existence.
Nicholas Galipeau, Senior Account Executive
Every AI vendor knows this, which is why Claude will refuse if you paste it your corporate card number and say "go shopping." The guardrails have to live somewhere - and the prompt is the wrong place, because the prompt is exactly what the agent might misread.
The four controls every buyer asks for
When we ask buyers what would make them comfortable, the answer is "all of the above": spend limits, approved merchants, human approval, and an audit trail. The audit trail ranks first, and the reason is regulatory, not technical.
This is a card tied to an agent, not to a person's name - KYC rules mean you can't issue a credit card to 'agent number five.' There's no personal responsibility. So the audit trail is everything: when the agent acted, what the logic was, the same way you read a model's reasoning trace when something looks off.
Emil Aite
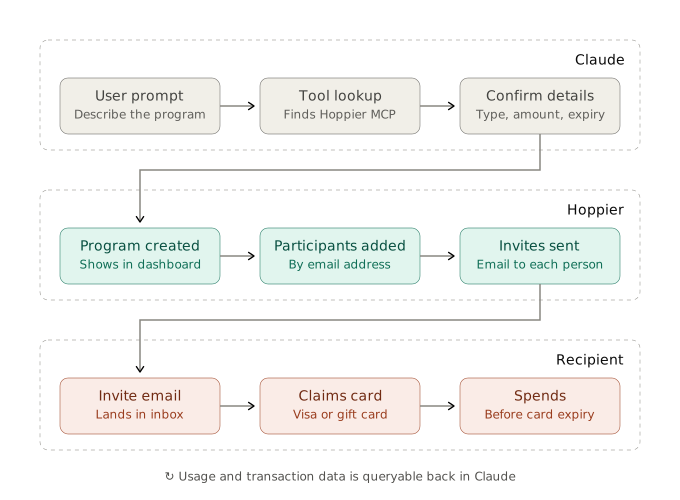
In practice the pattern that works is a one-time, virtually issued card per task: limited to one merchant category, one budget, one window. Here is what that looks like when Claude sets up an allowance through the Hoppier MCP:
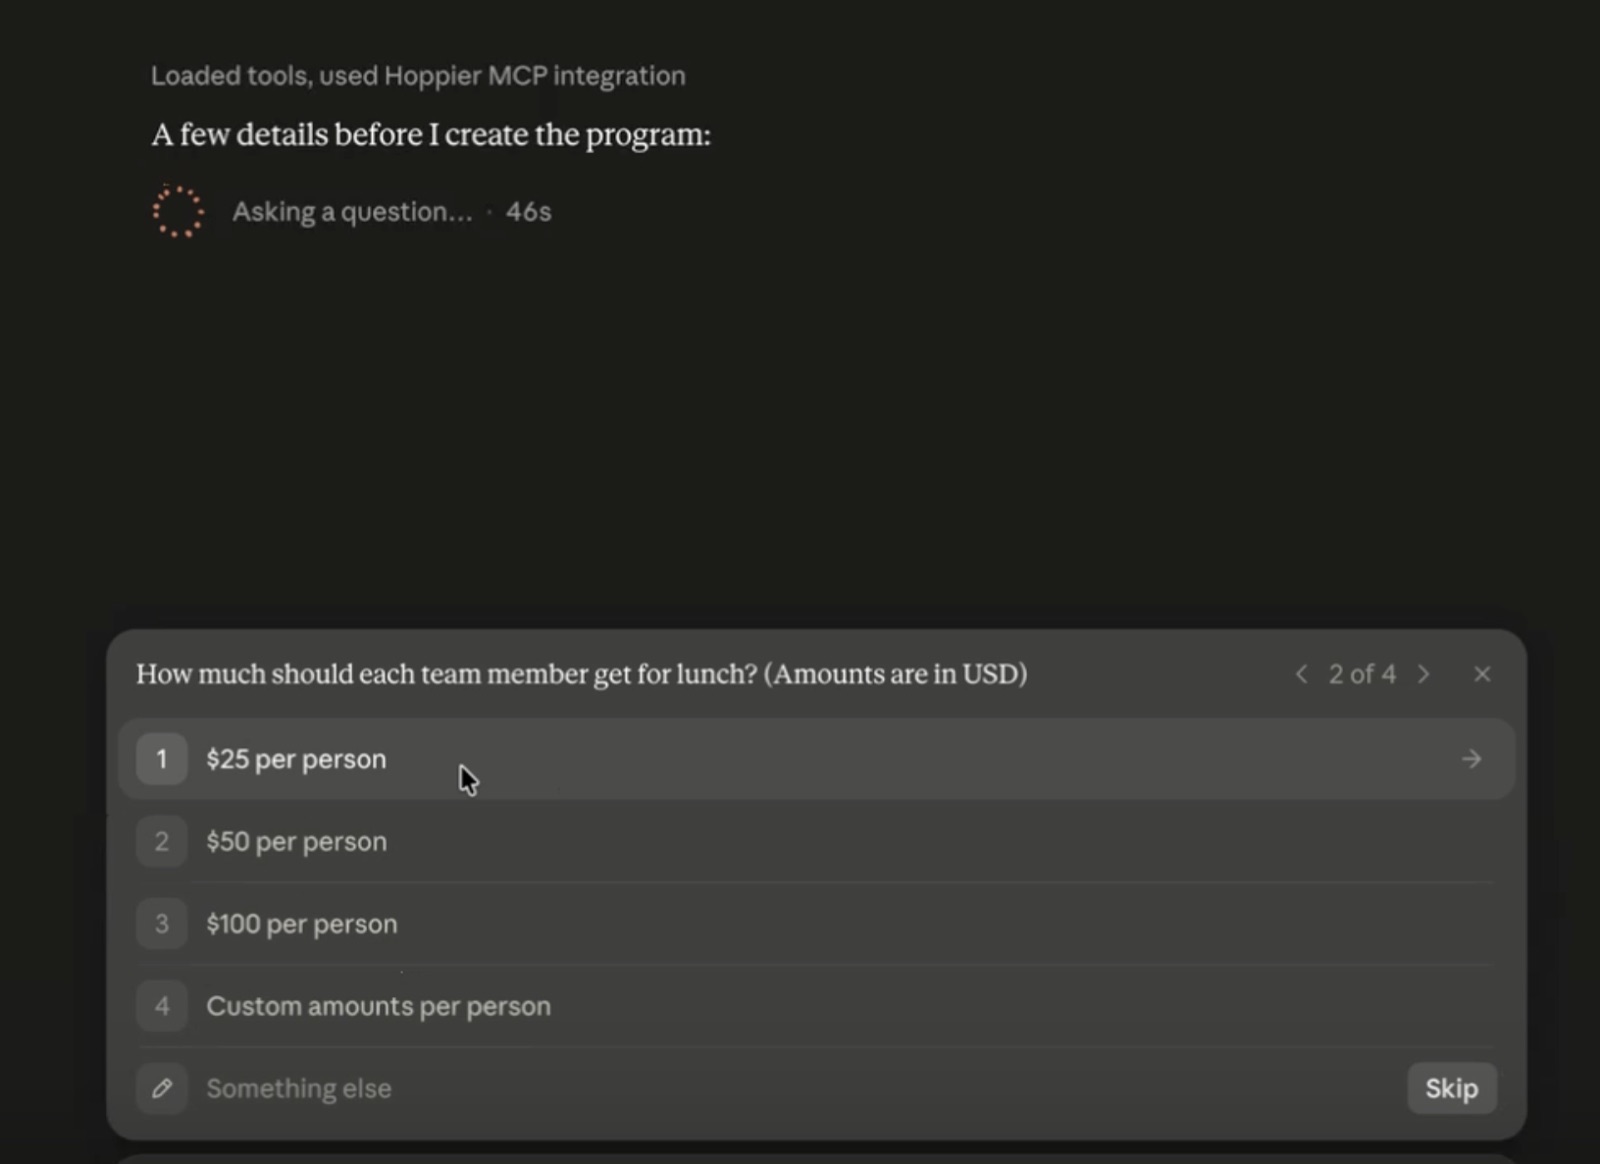
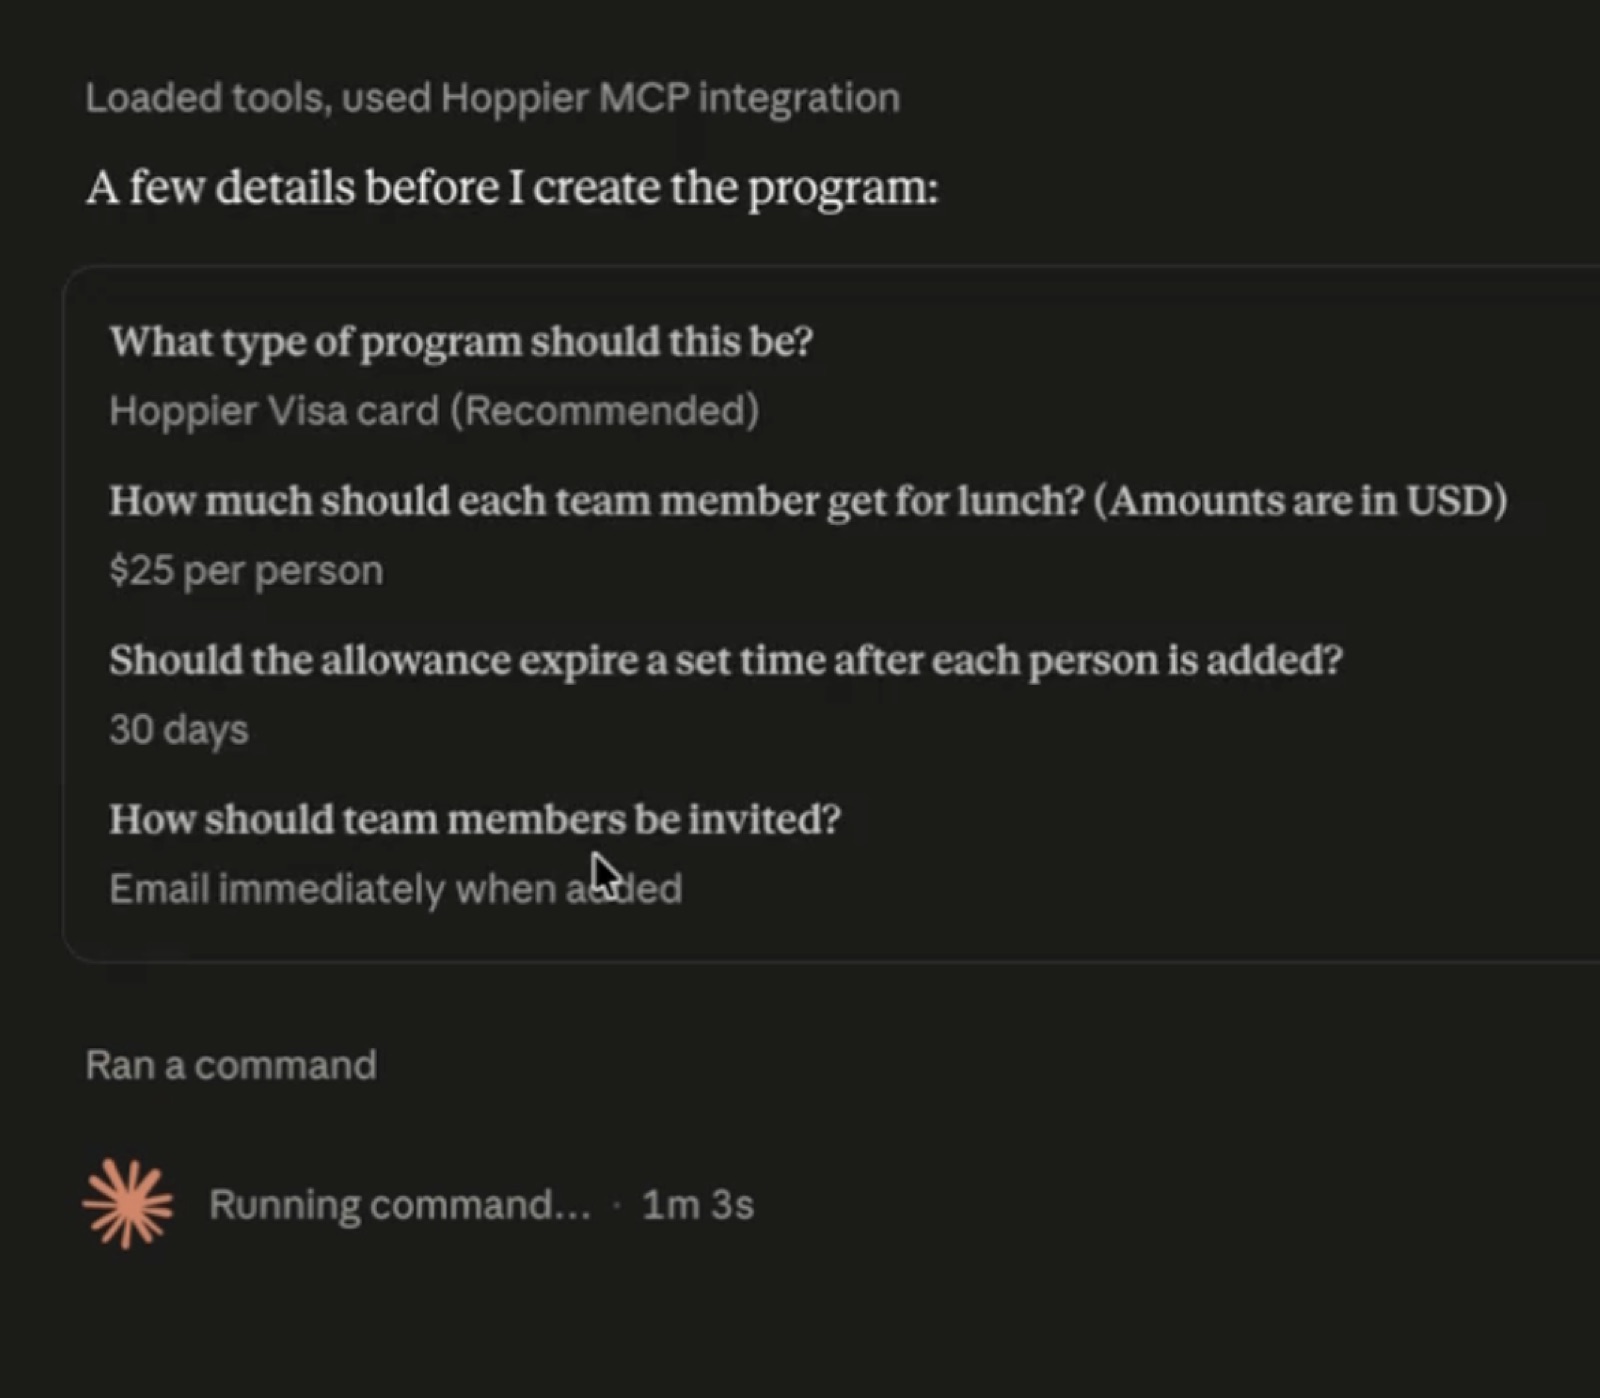
The human-approval step doesn't disappear - it moves. You verify the program rules with your own eyes once, then the agent operates freely inside them. Approval of the sandbox replaces approval of every purchase.
How the market defines it: Natural, Authorized, Skyfire
We read the people building this infrastructure and they disagree in useful ways.
Natural splits agentic payments into three categories - agent-to-agent, agent-to-business, agent-to-consumer - and argues the space should include banking, since agents will hold money, not just move it. They expect a shift from agent-initiated to agent-executed, then to agents on both sides of the transaction.
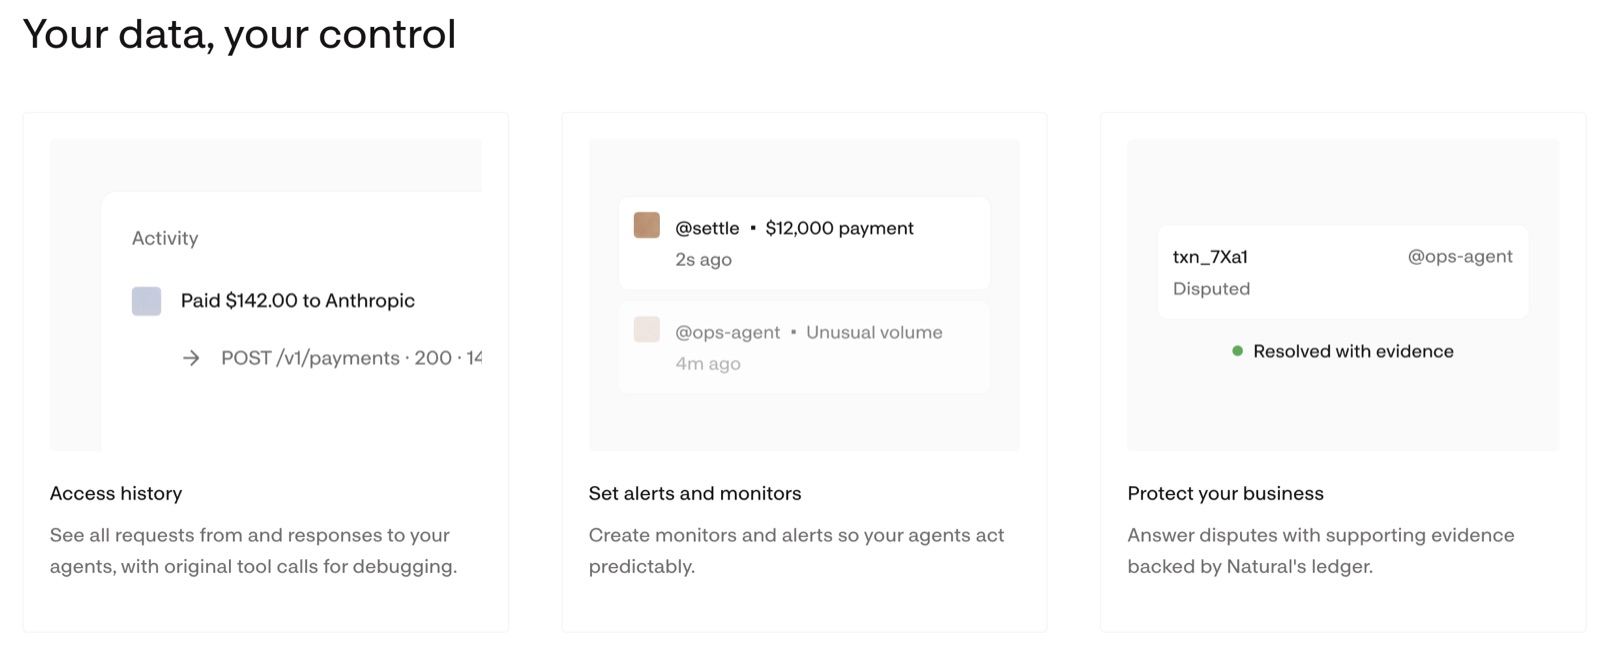
I think the three-way split is a little exaggerated. KYC is always attached to the consumer or the business - an agent can't open a bank account, because someone has to be legally responsible. So agent-to-agent and agent-to-business will probably collapse into the same thing: an autonomous layer buying on behalf of a person or company.
Emil Aite
Authorized takes the conservative corner: cards only, always a human in the loop, always human credentials. Skyfire takes the opposite bet - that payments become a backend function agents call without anyone thinking about it, the way you never watch your OS's background processes.
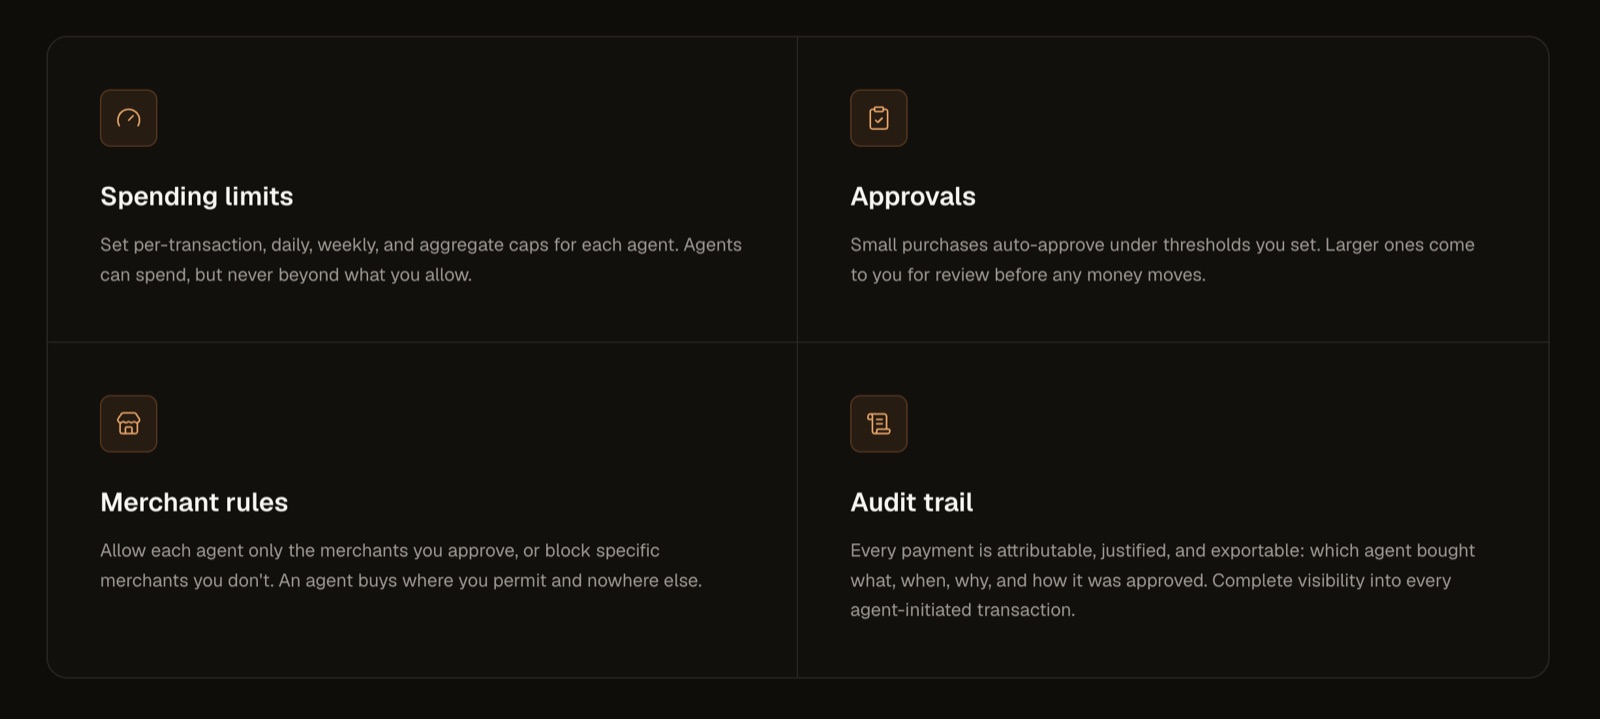
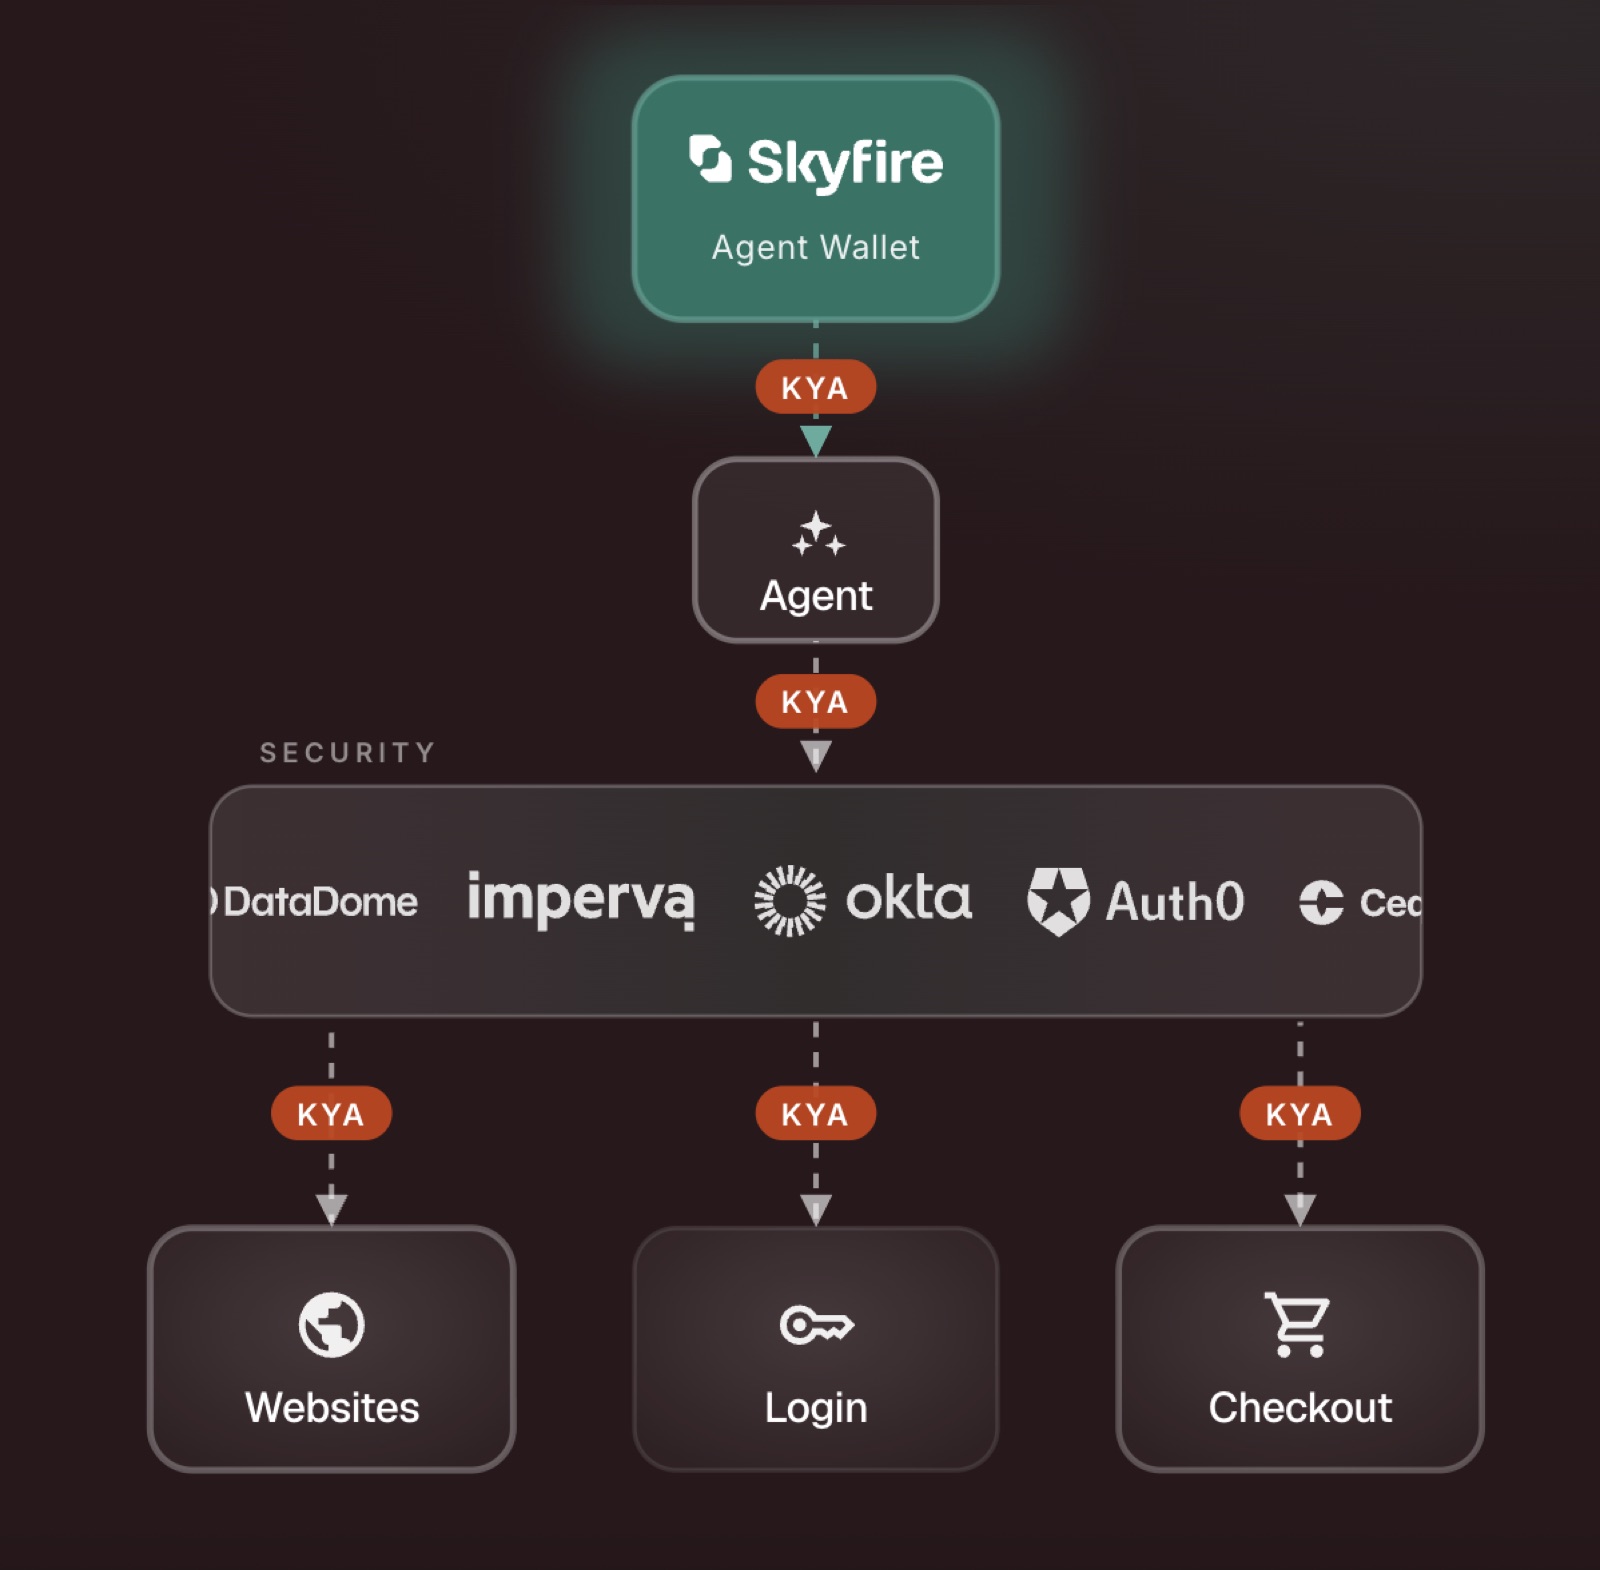
Two things the definitional debate tends to skip. First, the incumbents: Stripe issuing, Visa's and Mastercard's agent protocols, Coinbase and PayPal are all closer to the rails, and rails win on cost. Second, the rails themselves: US ACH is outdated and FedNow is slow to arrive, while UPI in India and PIX in Brazil already settle instantly - and an agent doesn't care how clunky a payment flow is. It will happily type the long account number. The convenience premium that card networks charge humans matters less when the buyer is software.
Real in 12 months vs. hype
Real: agent-to-business purchases with guardrails - the low-stakes, recurring spend. Groceries. The weekly team lunch. Ad budgets: agents already trigger usage-based billing every day, which is agentic spending by another name. Early adopters are already comfortable, and every major AI platform is racing to launch its version of background agents.
Hype: agent-to-agent payments - the robotaxi buying its own gas, one AI hiring another and settling up. Not because the technology is missing, but because the law is: money-movement rules require a responsible human or business on the account, and no regulator is about to let an agent take conscious responsibility. Agents will stay what they are today - an autonomous layer acting on behalf of someone with a name.
People do want to buy with agents. What's overhyped is connecting your banking or corporate card directly - everyone who has used AI for any amount of time has seen it make a considerable mistake, and you can imagine if every mistake cost real money.
Nicholas Galipeau
What you can do today: the sandbox pattern
Here is the version that works right now, with tools that exist. In Hoppier you create a program with a budget and merchant restrictions - and you can have Claude or ChatGPT create it for you, then verify the rules with your own eyes. Then you hand the card to an agent and let it run:
- Ad spend: a program approved for Facebook ads only, capped at $500 a month. Tell the agent to manage the campaign - it can never spend over the cap or outside the category.
- Team lunch: a monthly program restricted to restaurants and food delivery. The agent orders something new every week, like an EA would - on budget, every time.
- Rewards and incentives: the agent runs bulk sends, birthday programs, and SPIFFs through the Hoppier MCP, with per-card caps and full per-recipient tracking.
With Hoppier you're giving the agent a disposable card - a sandbox to function in, versus an open world where you've handed Claude your credit card and you're hoping. Worst comes to worst, the damage is limited to the program you set up.
Nicholas Galipeau
Spend limits, approved merchants, your own eyes on the rules, and a full audit trail - currency, location, timing, everything you'd expect from a card transaction. That's the whole stack, available today, without anyone's corporate Amex leaving the drawer. More on the architecture at hoppier.com/agentic-payments.
FAQ
What is agentic payments infrastructure?
The issuing, budgeting, restriction, and auditing layer that lets AI agents spend money safely on behalf of a person or business. It sits between the agent and the payment rails and enforces limits the agent cannot override.
Can an AI agent have its own bank account or credit card?
No. KYC and money-movement laws require a human or business to be legally responsible for every account. Agents operate on sandboxed, virtually issued cards tied to a real entity.
Are agent-to-agent payments real?
Not within the next year, in our view. The regulation isn't there, and in practice both "agents" resolve to a responsible human or company anyway - which makes it agent-to-business with extra steps.
How can I try agentic payments safely today?
Connect Claude or ChatGPT to the Hoppier MCP, have it create a program with a budget and merchant restrictions, verify the rules yourself, and let the agent run inside them. Setup takes about two minutes.
Make Hoppier your unfair advantage
Send rewards, gifts, and perks to employees, clients, and event attendees in 60+ countries - all from one platform.
Get Started